You did everything right. You carried insurance, you followed the rules of the road, and someone without insurance crashed into you anyway.
If you were hit by an uninsured driver in Michigan, your own no-fault personal injury protection, or PIP, usually pays your medical bills and lost wages regardless of who caused the crash, and uninsured motorist coverage on your policy may pay pain and suffering if you carry it. For Michigan drivers and accident victims trying to figure out who pays for medical care, missed work, car damage, and whether they can sue, that answer matters a lot.
It’s a common problem here. Roughly one in five Michigan drivers is uninsured, and the rate runs higher in some parts of metro Detroit. The good news is that Michigan’s no-fault system means you’re rarely left with nothing. Here’s who pays for what, when uninsured and underinsured motorist coverage applies, how vehicle damage claims work, when you may be able to sue the uninsured driver, and the steps to take after the crash.
Your Medical Bills and Lost Wages: Your Own No-Fault Insurance
In Michigan, your own personal injury protection (PIP) coverage pays your accident-related medical bills, a portion of your lost wages, and replacement services, and getting prompt medical treatment after the crash helps document your injuries and support the claim. It doesn’t matter who caused the crash, and it doesn’t matter whether the other driver had insurance. This is the part of the system that works in your favor.
If you don’t have your own auto policy, you may still be covered through:
- A spouse’s policy, or the policy of a relative you live with
- The insurance on the vehicle you were riding in
- The Michigan Assigned Claims Plan (MACP), if no other coverage applies
Two things to know about the MACP. First, medical benefits through the plan are capped at $250,000 in most cases, a limit the Department of Insurance and Financial Services confirms, so a catastrophic injury can exhaust it. Second, the application deadline is short and strictly enforced, so don’t wait.
One important exception applies across the board: if you owned a vehicle that was required to be insured and you didn’t insure it, Michigan law generally bars you from collecting PIP benefits for that crash. This is one of the harshest rules in the no-fault act, and it’s a big reason to keep coverage in place even on a car you rarely drive.
Your Pain and Suffering: Uninsured Motorist Coverage
In Michigan, these claims can include pain and suffering damages, but compensation for that loss normally comes from a claim against the at-fault driver’s liability insurance. When that driver has none, your best option is usually your own uninsured motorist (UM) coverage.
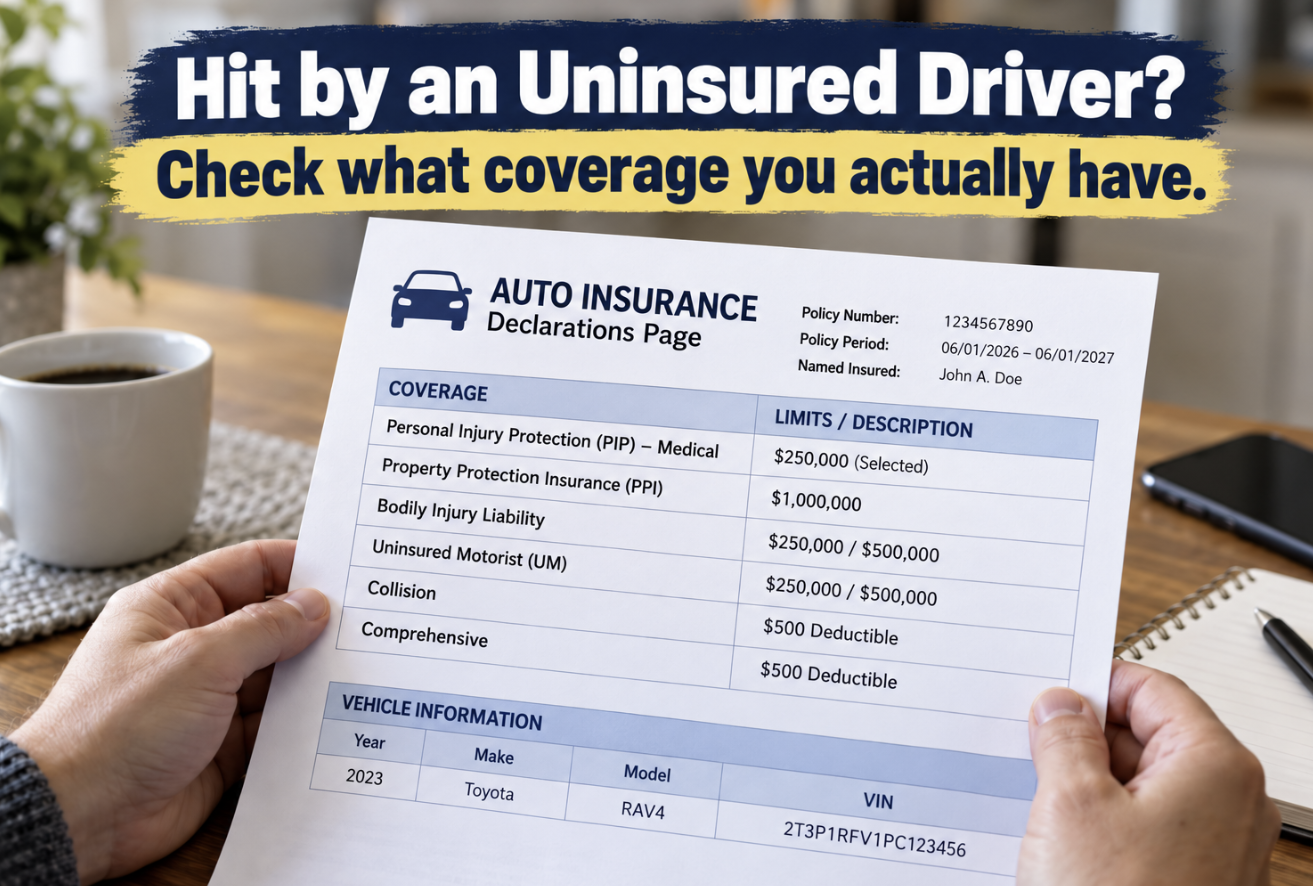
UM coverage is optional in Michigan. It isn’t required by law, and it has to be added to your policy, so check your declarations page. If you have it, that insurance coverage can cover pain and suffering when the other driver is uninsured and essentially pays what that driver’s insurance would have paid.
You still have to prove your case. That means showing the other driver was at fault, that you were not more than 50% at fault, and that your injury meets Michigan’s serious impairment threshold.
Two things to watch for in UM claims:
- Deadlines come from your policy, not a statute. UM is a contract claim, so your policy sets the notice requirements and the filing deadline, even though Michigan’s general contract statute of limitations is six years, and it can require earlier notice or suit than you’d expect.
- Set-Off Provisions. Some policies let the insurer deduct what they owe you from any PIP benefits already paid for your medical expenses and lost wages. The language varies by carrier and it’s worth having reviewed.
What If the Driver Had Insurance, Just Not Enough? Understanding Underinsured Motorist Coverage
That’s where underinsured motorist (UIM) coverage comes in. If the at fault driver’s insurance applies but isn’t enough to cover your losses, underinsured motorist coverage can make up the difference, up to your own limits. It fills the gap when your damages exceed the other driver’s policy limits.
This comes up more often than people expect. Under Michigan’s liability statute, the default bodily injury limits are $250,000 per person and $500,000 per accident, but drivers can sign a waiver to drop to $50,000 and $100,000. Against a serious injury, $50,000 disappears fast. Underinsured motorist claims usually require you to first exhaust the at-fault driver’s liability limits before turning to UIM coverage.
Like UM, underinsured coverage is optional, and it’s one of the least expensive ways to protect yourself and your family.
Can I Sue the Uninsured Driver Directly?
Yes. You can sue the at-fault driver personally for pain and suffering and for economic losses beyond what PIP covers, such as medical bills above your coverage limit or long-term wage loss caused by a negligent driver.
The practical problem is collecting. An uninsured driver often lacks the assets or income to satisfy a judgment, which can make a liability claim hard to collect even after you win in court, and a judgment you can’t collect doesn’t pay your bills. That’s a big part of why UM coverage matters so much in Michigan.
Your Vehicle Damage
Two possible sources here:
- Collision coverage on your own policy pays for vehicle repairs after an auto accident, subject to the deductible.
- Michigan’s mini tort provision lets you recover up to $3,000 from the at-fault driver. With an uninsured driver, though, there’s no insurer to bill, so you’d have to collect from the person directly, usually through small claims court.
What to Do Right Now
- Get a police report. It’s often the only official record of who the other driver was and whether they were insured, and it helps document the accident for insurance claims.
- Document the crash thoroughly. Take photos of vehicle damage and the scene, and get witness contact information while it’s still available.
- Notify your own insurer promptly, and tell your auto insurance company about the accident right away, especially for uninsured motorist claims or hit and run accidents.
- Request your declarations page so you know exactly what coverage you carry. Don’t rely on memory or on what an agent told you years ago.
- Keep treating, and follow your doctor’s instructions. Gaps in care get used against you later.
- Don’t give a recorded statement or sign a release until you understand your options.
- Talk to an attorney before any deadline passes.
Common Questions
Do I have to sue my own insurance company? Sometimes, and it feels wrong. But a UM claim is a contract claim, and your insurer is on the other side of it. Many are resolved without a lawsuit.
Will my rates go up if I make a UM claim? A claim for a crash you didn’t cause is treated differently than an at-fault accident. Fault determinations are what generally affect your rates.
What if I wasn’t in a car? Pedestrians and bicyclists struck by uninsured drivers can often claim PIP benefits through their own policy, a household member’s policy, or the MACP. UM coverage on your own auto policy may apply too.
I don’t think I have UM coverage. Is there anything I can do? Possibly. PIP still covers your medical bills and wage loss, you may have a claim against the driver personally, and there may be other sources of coverage depending on the circumstances. It’s worth having someone look at it.
Where can I get neutral information about my coverage? The Michigan Department of Insurance and Financial Services publishes consumer guides on auto insurance and answers questions by phone at 833-ASK-DIFS.
The Bottom Line
An uninsured driver doesn’t leave you without options in Michigan. Your PIP benefits cover your immediate medical needs and wage loss, and UM coverage, if you have it, can cover the pain and suffering an uninsured driver would otherwise never pay for.
These claims are against your own insurance company, which means the company you’ve been paying may be the one fighting you. Don’t take a denial at face value, and don’t let a policy deadline quietly expire.
Hit by an uninsured driver? Call Ruby Injury Law at 248-539-7439 for a free consultation. No fee unless we win.
About Ruby Injury Law — Ruby Injury Law is a Farmington Hills, Michigan personal injury firm founded by attorney Drew Ruby. The firm represents injured people across Michigan in auto negligence, food illness, and other injury claims. Call 248-539-7439 for a free consultation.
This article is for general information only and is not legal advice. Reading this article does not create an attorney-client relationship.